
Hyundai Financing and Trade-In: What to Do Before You Walk In
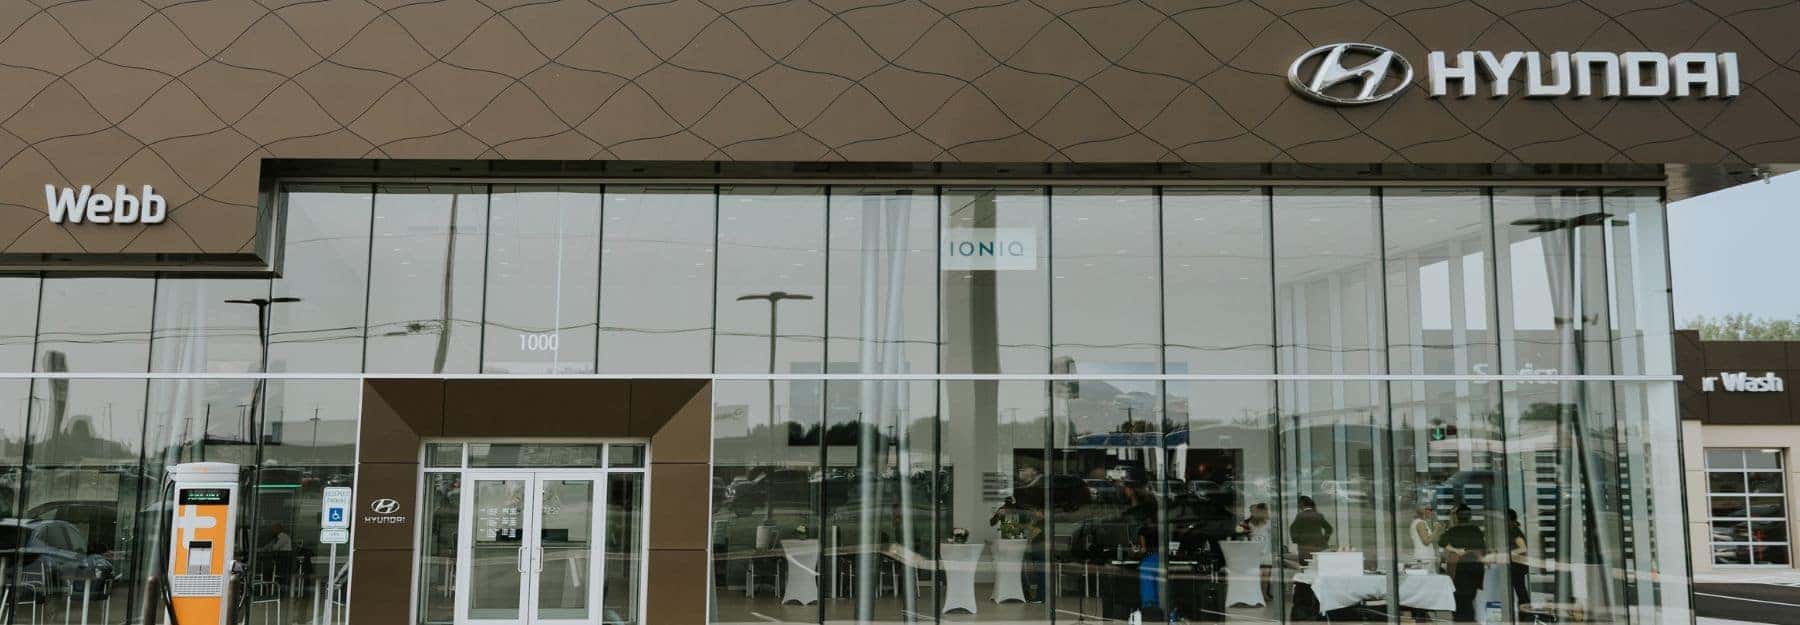
Most people spend weeks deciding which vehicle they want and about forty minutes thinking about how they are going to pay for it. That is backwards, and it is the reason the finance office feels stressful — it is the one part of the process nobody prepared for. The good news is that the financing and trade-in side of a purchase is far more predictable than it looks, and almost all of the leverage comes from things you can sort out before you ever walk in. This guide covers how dealership financing actually works at Webb Hyundai Merrillville, what determines your trade-in value, and the specific preparation that makes the paperwork go quickly.
How Does Dealership Financing Actually Work?
When you finance through a dealership, the dealership submits your application to multiple lenders — which can include the manufacturer’s finance arm, banks, and credit unions — and those lenders respond with the terms they are willing to offer. The dealership is acting as an intermediary rather than lending you the money itself. That structure is genuinely useful, because a single application can reach lenders you would otherwise have to approach one at a time.
- One application can be submitted to multiple lenders at once.
- Lenders respond with terms based on your credit profile, the vehicle, and the loan length.
- Manufacturer finance arms sometimes offer promotional terms that outside banks do not.
- You are free to decline dealership financing and use your own lender instead.
Should You Get Pre-Approved Before Visiting?
Pre-approval from your own bank or credit union is worth getting, because it gives you a concrete baseline to compare any dealership offer against. It costs you nothing but time, and it converts an abstract negotiation into a simple question: can the dealership beat the terms you already have? Sometimes it can, sometimes it cannot — either way you know where you stand rather than guessing.
- Gives you a real number to compare dealership offers against.
- Clarifies your realistic budget before you start looking at vehicles.
- Credit-scoring models generally treat multiple auto-loan inquiries in a short window as a single event, though the specifics vary by model — check with your lender if you are concerned.
- Bring the pre-approval paperwork with you.
What Does the Dealership See When It Checks Your Credit?
Lenders look at your credit score, your payment history, how much of your available credit you are using, the length of your credit history, and your debt-to-income ratio. Auto lenders also weigh your history with auto loans specifically, which is why someone with a thin overall file but a well-paid previous car loan can do better than expected. No single factor decides the outcome on its own.
- Payment history — the single most influential factor for most scoring models.
- Credit utilization — how much of your available revolving credit is in use.
- Length of credit history and the mix of account types.
- Debt-to-income ratio — how much of your monthly income is already committed.
- Prior auto loan history, which auto lenders weigh specifically.
What if Your Credit History Has Some Rough Patches?
A less-than-perfect credit history does not automatically rule out financing — lenders work across a wide range of credit profiles, and the terms offered simply reflect the risk they are taking on. What helps most is a larger down payment, a co-signer, proof of stable income, and being upfront about your situation so the finance team can approach the right lenders first. Being candid at the start saves everyone a round of declined applications.
- A larger down payment reduces lender risk and widens your options.
- Proof of steady income and time at your current job both carry weight.
- A co-signer with stronger credit can change what is available.
- Being upfront lets the finance team route your application efficiently.
What Determines Your Trade-In Value?
Trade-in value comes down to year, mileage, mechanical and cosmetic condition, trim and options, service history, and — often underestimated — current demand for that specific vehicle in this specific market. Two identical vehicles can appraise differently in different seasons or regions because demand genuinely differs. An appraisal is a real-time assessment, not a lookup in a fixed table.
- Mileage and age relative to what is typical for the model.
- Mechanical condition, including anything deferred or pending.
- Cosmetic condition — paint, panels, glass, wheels, and interior wear.
- Trim level and options, which can matter more than most sellers expect.
- Documented service history, which supports a stronger appraisal.
- Current local demand for that body style and powertrain.
How Do You Prepare a Vehicle for Appraisal?
Clean it thoroughly, gather every service record you have, bring both sets of keys, and fix the small inexpensive things — a burned-out bulb, a missing floor mat, a dead key fob battery. None of this changes the mechanical condition, but appraisals are partly a judgment about how the vehicle has been cared for, and presentation genuinely informs that judgment. Do not spend real money on major repairs before an appraisal without asking first.
- Clean inside and out and remove personal belongings.
- Gather service records, the owner’s manual, and the title or loan information.
- Bring all keys and remotes — missing ones are a common deduction.
- Replace missing floor mats, cargo covers, and headrests if you have them.
- Ask before paying for any significant repair — it may not return its cost.
What Happens if You Owe More Than the Trade Is Worth?
This situation — commonly called negative equity or being “upside down” — is common, particularly on newer loans, and it does not prevent a trade. The remaining balance is either paid out of pocket or rolled into the new loan, and rolling it in increases what you finance on the new vehicle. It is worth understanding clearly before you commit, because the effect carries forward into the next loan.
- Request your current payoff amount from your lender before you shop.
- Compare that payoff to a realistic appraisal range for your vehicle.
- Understand whether any shortfall is being paid up front or added to the new loan.
- Ask the finance team to show you exactly how it is being handled.
How Is Leasing Different From Financing?
Financing builds toward ownership — you make payments and eventually own the vehicle outright. Leasing is closer to a long-term rental: you pay for the vehicle’s use over a set term and mileage allowance, then return it, buy it, or start a new lease. Neither is universally better; the right choice depends on how many miles you drive, how long you keep vehicles, and whether ownership matters to you. Terms, mileage allowances, and end-of-lease conditions vary, so review the specifics carefully.
What Documents Should You Bring?
Bring your driver’s license, proof of current insurance, recent proof of income, and — if trading — the vehicle’s title or lender information plus all keys. Having these together is the difference between finishing in one visit and making a second trip. If you have a pre-approval, bring that paperwork as well.
What Should You Ask Before You Sign?
Ask for the total amount financed, the term length, the annual percentage rate, whether there is a prepayment penalty, and exactly what any optional products cover. Every one of those should be answered plainly and in writing before you sign anything. If an answer is unclear, that is a reason to slow down rather than a reason to move faster.
- What is the total amount financed, and what is included in it?
- What is the term length and the annual percentage rate?
- Is there a prepayment penalty if I pay the loan off early?
- Which items on this contract are optional, and what does each one cover?
- How is my trade-in payoff being handled?
Quick Overview: Financing and Trade-In Preparation
| Step | Do This Before You Visit | Why It Matters |
|---|---|---|
| Check your credit | Pull your own report and review it | No surprises; you can correct errors first |
| Get pre-approved | Apply at your bank or credit union | Gives you a baseline to compare against |
| Get your payoff | Call your current lender | Tells you your real trade position |
| Prep the trade | Clean it; gather records and all keys | Presentation informs the appraisal |
| Gather documents | License, insurance, income, title | Turns two visits into one |
How to Prepare for Financing at Webb Hyundai Merrillville
- Review your own credit report and dispute anything inaccurate before you apply.
- Get pre-approved through your bank or credit union so you have a comparison point.
- Request your payoff amount from your current lender if you are trading.
- Clean and prepare your trade-in, gathering records and all keys and remotes.
- Collect your documents — license, insurance, proof of income, title or loan info.
- Browse inventory first at Webb Hyundai Merrillville, or call (219) 736-2277.
- Ask for everything in writing and read it before signing.
Key Takeaways
- Dealership financing submits one application to multiple lenders, which is a genuine convenience advantage.
- Outside pre-approval costs nothing and gives you a concrete baseline to compare against.
- Payment history, credit utilization, debt-to-income, and prior auto loans all feed the decision.
- Imperfect credit does not rule out financing; a larger down payment and candor about your situation help most.
- Trade value reflects condition, mileage, trim, service history, and current local demand — it is a real-time assessment.
- Negative equity is common and manageable, but understand exactly how any shortfall is being handled.
- Bring license, insurance, proof of income, title or loan info, and all keys to finish in one visit.
Frequently Asked Questions
Do I need perfect credit to finance a Hyundai?
No. Lenders work across a wide range of credit profiles, and your credit history affects the terms you are offered rather than whether financing is possible at all. A larger down payment, proof of stable income, or a co-signer can all improve the options available to you.
Can I trade in a vehicle I still owe money on?
Yes. The dealership works with your lender to handle the payoff. If the vehicle appraises for more than you owe, the difference goes toward your new purchase; if you owe more than it is worth, the shortfall is either paid out of pocket or added to the new loan. Ask to see exactly how it is being handled.
Should I get my own financing before coming in?
It is worth doing. A pre-approval from your bank or credit union gives you a concrete set of terms to compare any dealership offer against, which makes the conversation much simpler. You are always free to use whichever option turns out to be better for you.
Does cleaning my car before a trade-in appraisal actually matter?
It genuinely can. An appraisal is partly a judgment about how well the vehicle has been maintained, and presentation informs that judgment. Cleaning it, gathering service records, and bringing all keys and remotes are low-cost steps. Avoid paying for major repairs beforehand without asking, since they may not return their cost.
What documents do I need to bring?
Bring your driver’s license, proof of current insurance, recent proof of income, and — if you are trading a vehicle — its title or your lender’s information along with all keys and remotes. If you have a pre-approval from another lender, bring that paperwork too.
Come in prepared and the paperwork stops being the stressful part.
0 comment(s) so far on Hyundai Financing and Trade-In: What to Do Before You Walk In